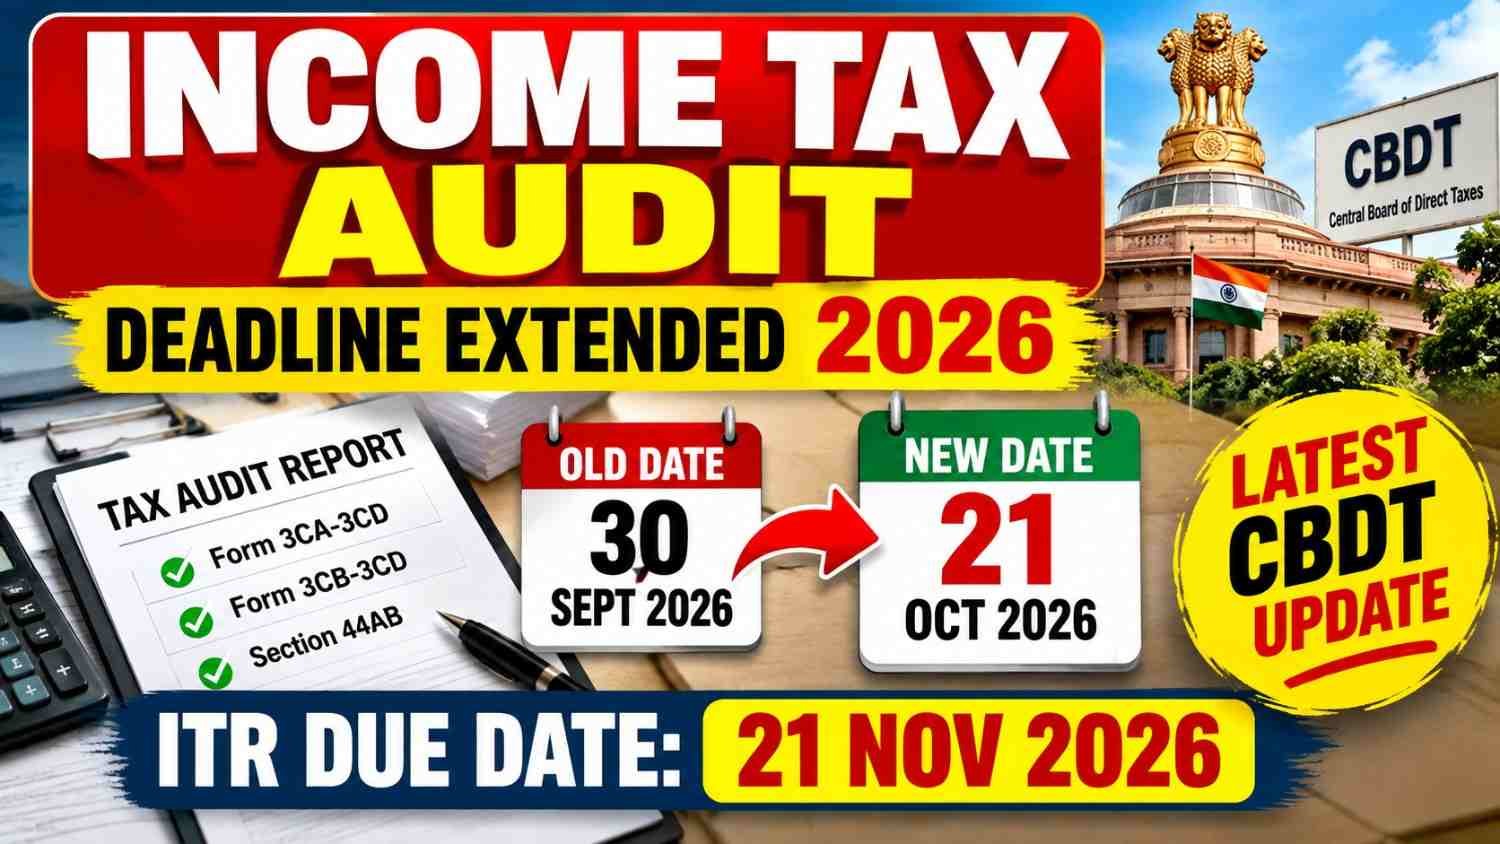
The income tax audit deadline has been extended for certain taxpayers for Assessment Year (AY) 2026-27. On 28 September 2026, the Central Board of Direct Taxes (CBDT) announced that the due date for furnishing the tax audit report has been moved from 30 September 2026 to 21 October 2026 for the taxpayers covered by the specified provision.
The corresponding deadline for filing the Income Tax Return (ITR) for the affected audit cases has also been extended from 31 October 2026 to 21 November 2026. The extension gives eligible taxpayers and tax professionals additional time to complete audit-related compliance and file the return.
Latest update: The CBDT announcement was made on 28 September 2026. The department stated that a formal order/notification giving effect to the extension would be issued separately. Taxpayers should therefore check the official Income Tax Department portal for the formal notification and detailed applicability.
Income tax audit Latest News 2026: What Changed on 28 September
The latest income tax audit development concerns taxpayers whose accounts are required to be audited and who fall within the category covered by the relevant provision of Section 139(1).
According to the CBDT announcement reported on 28 September 2026:
- Earlier tax audit report date: 30 September 2026
- Revised tax audit report date: 21 October 2026
- Earlier ITR due date for the relevant audit cases: 31 October 2026
- Revised ITR due date for the relevant audit cases: 21 November 2026
- Extension announced: 21 days
- Assessment Year: AY 2026-27
The extension applies to the specified category covered under the relevant provision and is not a blanket extension for every taxpayer.
Income tax audit Deadline 2026: New Due Dates You Need to Know
The revised income tax audit schedule can be understood as follows:
Tax Audit Report
Earlier date: 30 September 2026
New date: 21 October 2026
Income Tax Return for applicable audit cases
Earlier date: 31 October 2026
New date: 21 November 2026
This means eligible taxpayers receive an additional 21 days for completing the audit-report requirement, followed by additional time for filing the corresponding ITR.
Income tax audit Who Is Covered by the 2026 Extension
The income tax audit extension is specifically linked to taxpayers covered by Sl. No. 2 in the Table under Explanation 2 to Section 139(1) of the Income-tax Act, 1961, where the provisions of Section 92E do not apply.
In practical terms, the extension is aimed at taxpayers whose income-tax returns are subject to the audit-related filing timeline under the specified provision. It should not automatically be interpreted as an extension for every type of audit report or every taxpayer.
Taxpayers involved in international or specified domestic transactions requiring a report under Section 92E should carefully verify their separate compliance timeline rather than assuming that this announcement changes their deadline.
Income tax audit Forms for AY 2026-27: Form 3CA-3CD and Form 3CB-3CD
For FY 2025-26 corresponding to AY 2026-27, the income tax audit continues to be governed by the Income-tax Act, 1961 for the purpose of the tax audit report.
The Income Tax Department states that:
- Form 3CA-3CD applies where the taxpayer’s accounts are already required to be audited under another law.
- Form 3CB-3CD applies where the taxpayer is required to obtain a tax audit under Section 44AB but is not required to have the accounts audited under another law.
- The Chartered Accountant submits the applicable audit report through the e-Filing portal.
The Income Tax Department’s current guidance specifically confirms that the FY 2025-26/AY 2026-27 tax audit report uses the existing Forms 3CA/3CB and Form 3CD under the 1961 Act.
Income tax audit Threshold: Who Generally Needs a Tax Audit
The income tax audit requirement under Section 44AB generally applies when specified turnover, sales or gross-receipt conditions are crossed, subject to the conditions prescribed under law.
According to the Income Tax Department’s guidance, the broad thresholds are:
For business: Tax audit is generally required when sales, turnover or gross receipts exceed ₹1 crore. The threshold can go up to ₹10 crore where cash receipts and cash payments do not exceed the specified 5% limits.
For profession: Tax audit is generally required when gross receipts exceed ₹50 lakh, subject to the applicable provisions.
There are also tax-audit requirements in certain situations involving presumptive taxation and declaring income below the prescribed level. The exact applicability depends on the taxpayer’s circumstances.
Income tax audit Why the Deadline Was Extended
The income tax audit extension comes after tax professionals and professional organisations had been seeking additional time to complete audit-related compliance.
Reports on the CBDT decision indicate that the extension was intended to provide additional time to taxpayers and professionals dealing with the compliance cycle. The CBDT has extended the relevant audit-report timeline by 21 days and the corresponding ITR deadline by 21 days.
The extension is particularly relevant because tax audit work involves reconciliation of financial statements, tax records, deductions, TDS information, reporting requirements and other particulars before the final return is submitted.
Income tax audit What Businesses Should Do After the Extension
Even after the income tax audit deadline extension, taxpayers should not wait until the new deadline.
Businesses and professionals covered by tax audit should:
- Complete the books of accounts and financial reconciliation.
- Check sales, turnover and gross-receipt figures.
- Reconcile bank transactions.
- Verify cash receipts and cash payments.
- Reconcile TDS and other tax-related information.
- Review GST and accounting records wherever applicable.
- Provide required documents and explanations to the Chartered Accountant.
- Review the draft audit report carefully.
- Ensure the applicable audit form is submitted through the e-Filing portal.
- Prepare the ITR using the information reported in the audit documentation.
- Complete ITR filing within the revised applicable deadline.
- Keep copies of the filed forms, acknowledgement and supporting records.
The Income Tax Department has also been sending reminders encouraging taxpayers to file audit reports before the earlier 30 September deadline. Those reminders were issued before the 28 September extension announcement, so taxpayers should follow the latest formal CBDT order once issued.
Income tax audit New Deadline: 21 October 2026 Explained
The most important income tax audit date in the latest announcement is 21 October 2026.
For taxpayers covered by the CBDT extension, the tax audit report that was previously due on 30 September 2026 can now be furnished by 21 October 2026.
The corresponding ITR deadline for the relevant taxpayers moves to 21 November 2026.
This does not mean that every income-tax-related deadline in 2026 has been moved to these dates. The extension applies to the specified category covered by the CBDT announcement.
Income tax audit Penalty: What Happens if You Miss the Deadline
The income tax audit deadline should still be taken seriously even after the extension.
Under the tax-audit provisions, failure to get accounts audited or furnish the audit report as required can attract consequences under the Income-tax law. The commonly cited penalty provision under the earlier law is Section 271B, subject to the statutory conditions and reasonable-cause provisions.
Because the 2026 tax framework involves the transition from the Income-tax Act, 1961 to the Income-tax Act, 2025, taxpayers should obtain professional advice regarding the exact consequence applicable to their particular default and assessment year.
A taxpayer should not assume that a delay is automatically penalty-free simply because the CBDT has granted an extension.
Income tax audit AY 2026-27: Old Act or New Act?
The income tax audit position for AY 2026-27 is important because India has transitioned to the Income Tax Act, 2025.
The Income Tax Department’s own guidance clarifies that the tax audit report relating to FY 2025-26 and AY 2026-27 continues under the Income-tax Act, 1961, even if the report is filed after 1 April 2026.
For this assessment year, the applicable audit forms remain Form 3CA-3CD or Form 3CB-3CD, as applicable.
For the subsequent Tax Year 2026-27 under the Income Tax Act, 2025, the Income Tax Department says the tax audit report will use Form No. 26, which combines the earlier audit-report structure, with the applicable due date stated as 30 September 2027.
Income tax audit 2026: Important Difference Between AY 2026-27 and Tax Year 2026-27
The income tax audit terminology can become confusing because the tax system has transitioned to the Income Tax Act, 2025.
For FY 2025-26 / AY 2026-27, the relevant tax audit report continues under the Income-tax Act, 1961.
For the Tax Year 2026-27, the new Income Tax Act, 2025 framework applies.
Therefore, taxpayers should identify the correct financial year and assessment/tax year before selecting forms or calculating deadlines.
Income tax audit Latest Update: What Taxpayers Should Remember
The key income tax audit update on 28 September 2026 is that CBDT has announced a 21-day extension for the specified audit cases.
The revised dates announced are:
Tax Audit Report: 21 October 2026
ITR for the relevant audit cases: 21 November 2026
The extension is not a universal extension covering all taxpayers and all types of tax reports. Taxpayers should verify whether their particular case falls within the category specified by CBDT.
The CBDT has also indicated that a formal order/notification will be issued separately. Therefore, taxpayers should rely on the final notification and the official Income Tax Department e-Filing portal when completing their compliance.
Income tax audit FAQs: Frequently Asked Questions
income tax audit FAQ: What is the new tax audit deadline for AY 2026-27?
For the taxpayers covered by the CBDT’s 28 September 2026 extension, the tax audit report deadline has been moved from 30 September 2026 to 21 October 2026.
Income tax audit FAQ: What is the new ITR deadline for audit cases?
For the relevant taxpayers covered by the extension, the ITR deadline has been moved from 31 October 2026 to 21 November 2026.
Income tax audit FAQ: Is the extension applicable to everyone?
No. The CBDT announcement applies to the specified category of taxpayers covered by the relevant provision of Section 139(1), where Section 92E does not apply. Taxpayers should verify their individual applicability.
Income tax audit FAQ: Which forms are used for AY 2026-27?
For FY 2025-26/AY 2026-27, the applicable tax audit forms are Form 3CA-3CD or Form 3CB-3CD, depending on the circumstances of the taxpayer.
Income tax audit FAQ: Does the new Income Tax Act apply to the AY 2026-27 audit report?
The Income Tax Department states that the FY 2025-26/AY 2026-27 tax audit report remains under the Income-tax Act, 1961, even where filing occurs after 1 April 2026.
Income tax audit FAQ: Has the government officially extended the deadline?
Yes, CBDT announced the extension on 28 September 2026. However, the announcement stated that a formal order/notification would be issued separately. Taxpayers should check the official notification when published.
Income tax audit Conclusion: 2026 Deadline Extension
The latest income tax audit news provides additional compliance time to taxpayers covered by the CBDT’s 28 September 2026 announcement.
For the specified AY 2026-27 audit cases, the tax audit report deadline moves to 21 October 2026, while the corresponding ITR deadline moves to 21 November 2026.
Taxpayers should use the additional time to complete accounting reconciliation, coordinate with their Chartered Accountant, verify tax information and submit accurate reports. The extension should not be treated as a reason to postpone compliance until the final day.
Because the CBDT stated that the formal order/notification would follow separately, taxpayers should verify the final notification and applicability on the official Income Tax Department portal before relying on the revised dates for their specific case.
Disclaimer: This article is intended for general informational purposes and should not be treated as professional tax or legal advice. Taxpayers should verify the latest CBDT notification and consult a qualified Chartered Accountant or tax professional for case-specific compliance.